Market overview of the Custom Jewelry Service Market
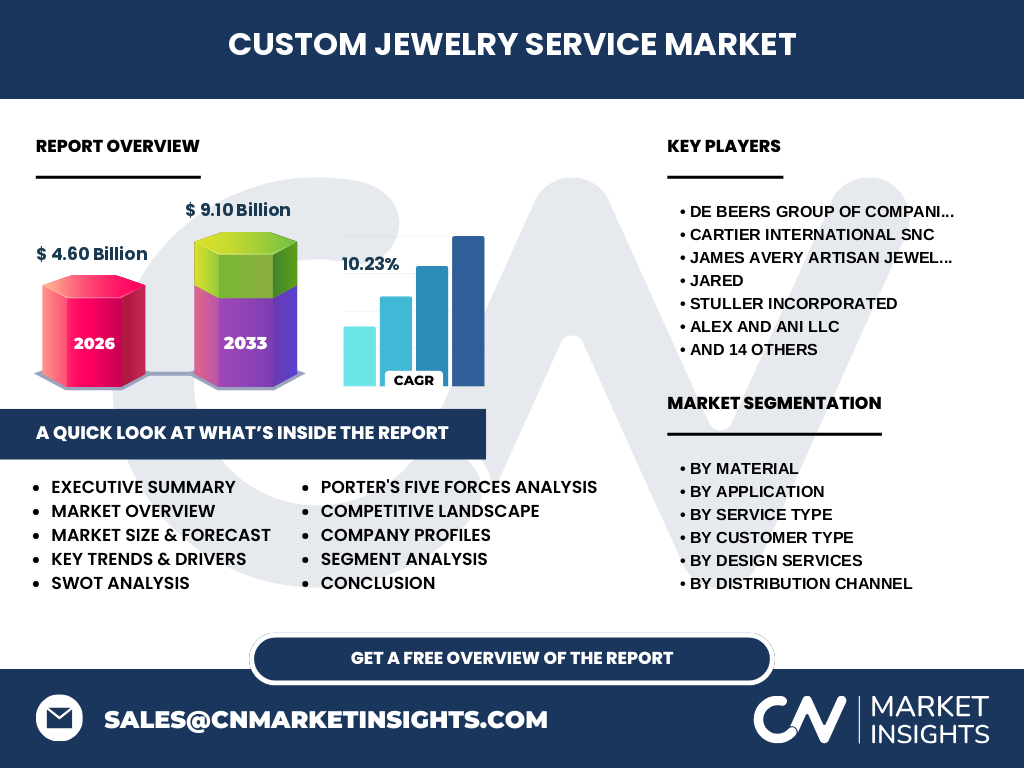
The Custom Jewelry Service Market represents a sophisticated segment of the luxury sector, valued at 4.60 Billion in 2026. It encompasses specialized services from bespoke design to complex manufacturing. The industry provides significant value by bridging the gap between raw artisanal craftsmanship and modern Computer-Aided Design (CAD), enabling consumers to transition from mass-produced retail to highly personalized, meaningful jewelry pieces.
Structural Growth Drivers, Restraints, and Opportunities
Growth is primarily driven by a consumer shift toward hyper-personalization and unique storytelling. While high volatility in precious metal prices and regulatory scrutiny by the Responsible Jewellery Council act as restraints, massive opportunities exist. Innovations in 3D printing and direct-to-consumer digital platforms allow firms like Stuller Incorporated to scale production efficiently, overcoming traditional logistical hurdles in inventory management.
Emerging trends and growth patterns in Custom Jewelry Service
The trend toward sustainable luxury is reshaping the market. Consumers increasingly demand transparency in sourcing diamonds and gemstones. Our analysis shows a significant rise in digital render previews, allowing clients to iterate on designs before casting. This tech-forward approach reduces waste and aligns with the operational agility demonstrated by innovators such as VRAI Labs Private Limited.
Impact of COVID-19 and the recovery trajectory
The pandemic initially paralyzed physical retail, yet the Custom Jewelry Service Market demonstrated resilience through accelerated digitalization. Post-2020, firms pivoted to virtual consultations and secure e-commerce portals. This recovery trajectory is evidenced by the rapid adoption of remote collaboration tools, allowing companies to maintain global supply chains despite localized lockdowns at major jewelry manufacturing hubs like Mumbai and Antwerp.
Competitive landscape and strategic dynamics
The market is highly fragmented, featuring a mix of legacy titans like De Beers Group and agile boutiques like Bamina Jewelry. Concentration is highest in the manufacturing segment, where firms with deep casting and molding capabilities dominate. Strategic competition is currently focused on vertical integration, where players control the value chain from rough stone procurement to final custom delivery.
Executive Summary: High-level market synthesis
The Custom Jewelry Service Market is poised for significant expansion, reaching a projected 9.10 Billion by 2033. With a robust CAGR of 10.23%, the sector is transitioning from traditional bench work to a high-tech, service-oriented model. Success in this landscape requires a dual focus: maintaining exquisite handcrafted production standards while leveraging scalable CAD-based manufacturing to satisfy modern consumer demands for rapid, bespoke delivery.
Market forecast from 2027 to 2033
Our projections indicate that the market will maintain a steady 10.23% CAGR between 2027 and 2033. This growth is anchored by expanding individual consumer wealth and corporate interest in customized institutional gifting. By 2033, we anticipate the market size reaching 9.10 Billion, driven by increased penetration of 3D printing technologies in secondary tier cities globally.
Segmentation analysis by material and application
Segmentation provides critical clarity: Gold and Diamonds remain the dominant material segments, serving as both luxury status symbols and financial assets. By application, the Ring segment continues to lead in volume, particularly within the bridal category. Meanwhile, bracelets and necklaces are seeing increased traction as customization platforms allow for more complex geometric designs that were previously difficult to manufacture by hand.
Regional market analysis and geographic performance
North America and Europe currently lead, driven by high disposable income and established luxury retail networks. However, the Asia-Pacific region is emerging as a high-growth hub, supported by sophisticated manufacturing ecosystems in India and China. Regional performance is heavily dictated by the proximity to raw material trade centers and the local regulatory environment governing gemstone certification and precious metal import duties.
In-depth review of regional market dynamics
In North America, demand for Repair and Alteration Services like stone replacement is surging as consumers seek to upcycle family heirlooms. Conversely, the Asia-Pacific region shows a clear preference for Design Services, specifically custom 18k gold pieces. This contrast demonstrates how localized cultural heritage shapes the specific service types that thrive within each regional framework.
Company profiles and strategic positioning
Industry leaders like Tacori Enterprises Incorporated emphasize brand prestige, whereas JewelPin and Maroth Jewels Private Limited focus on cost-effective, high-volume custom manufacturing for B2B clients. MiaDonna and Company has carved a niche in lab-grown diamonds, appealing to ethically conscious consumers. This diverse positioning allows companies to mitigate risk while targeting specific demographics within the broader custom jewelry ecosystem.
Porter's Five Forces analysis of the market
The Custom Jewelry Service Market faces intense competitive rivalry due to low entry barriers for small boutiques. However, the bargaining power of suppliers remains high due to the limited supply of high-grade, conflict-free gemstones. Threat of substitutes is moderate, restricted mainly to mass-market retail jewelry, which cannot replicate the emotional value and specific bespoke design features offered by custom providers.
SWOT analysis: Strengths, Weaknesses, Opportunities, and Threats
Strengths include high customer loyalty driven by personalization. Weaknesses involve long lead times for complex handcrafted production. Opportunities lie in the integration of AI-driven digital render previews to accelerate client approvals. Threats persist in the form of fluctuating commodity prices and potential supply chain disruptions at major global trading hubs, which could jeopardize delivery timelines and increase production costs.
Value chain analysis and industry structure
The value chain originates with raw material extraction and trade, flowing into design services, where value is added through creative intellectual property. Manufacturing—whether through casting, molding, or 3D printing—serves as the primary value-adding node. Finally, distribution channels, including both physical boutiques and direct-to-consumer digital platforms, deliver the finished custom jewelry to end-users, capturing the final margin in the product lifecycle.
Investment insights and high-potential areas
We identify Consultation Services and CAD-based custom design software as high-potential investment areas. Companies that successfully implement style advisory alongside budget planning tools see significantly higher conversion rates. Furthermore, early-stage capital allocated to sustainable jewelry technologies—specifically those reducing water and chemical usage during casting—represents a strategic move to capitalize on long-term environmental, social, and governance (ESG) compliance trends.
Conclusion and key takeaways
The Custom Jewelry Service Market is experiencing a fundamental transformation, moving toward a 9.10 Billion valuation by 2033. The key to capturing this value is the successful synthesis of heritage craftsmanship and modern digital efficiency. Stakeholders must prioritize transparency and technological agility to remain competitive in this increasingly sophisticated and personalization-focused market.
Research methodology for the market report
Our methodology utilizes a triangulated approach, synthesizing data from global trade registries, primary interviews with lead designers, and secondary macroeconomic indicators. We cross-reference shipping logs from major ports with regional consumer spending surveys to calibrate baseline estimates. This rigorous process ensures that the 4.60 Billion market size reflects a comprehensive assessment of both formal enterprise activity and boutique artisanal output.
Scope of the report: Parameters and limitations
This report evaluates the global Custom Jewelry Service Market, focusing on services ranging from consultation and design to manufacturing and repair. The analysis covers key material segments, including gold, platinum, and gemstones. Limitations include the exclusion of informal, unregistered small-scale craftsmen who do not contribute to standardized trade statistics, ensuring the findings represent the institutional and high-growth segments of the industry.
Recent developments and strategic moves in the industry
Recent activity is defined by strategic partnerships between technology providers and luxury jewelers. For example, the adoption of blockchain for gemstone traceability is becoming a common industry announcement. Furthermore, recent product launches by companies like Pyrrha Jewelry highlight the trend toward narrative-driven, personalized jewelry, while tactical expansions into 3D printing hubs are signaling a shift toward localized, on-demand production models to minimize logistics friction.